Navigating capital gains taxes in India is a critical aspect of wealth creation. Many investors watch their portfolios grow but are shocked by their tax liabilities when they eventually redeem their investments. Fortunately, utilizing a strategy like tax harvesting mutual funds can help you legally optimize your returns and reduce your tax burden.
By understanding how capital gains are taxed and using simple allocation adjustments, you can reset your cost basis and save substantial amounts of money over time.
How Tax Harvesting Mutual Funds Works for Small Portfolios
In India, equity mutual fund gains on investments held for more than 12 months are classified as Long-Term Capital Gains (LTCG). Under the current tax rules, LTCG on equity assets is completely tax-exempt up to an annual limit of ₹1.25 lakhs. Any gains above this threshold are taxed at a flat rate of 12.5%.
For investors with small portfolios, tax harvesting mutual funds is a highly effective wealth-accelerating tool:
- Book the Profits: Before the end of each financial year, identify mutual fund units held for over one year that have accumulated capital gains.
- Redeem Up to the Limit: Sell enough units to realize long-term capital gains up to the ₹1.25 lakhs tax-free limit.
- Immediately Reinvest: Withdraw the money and reinvest it back into the same or similar mutual funds.
Because you realized the gains tax-free, you successfully reset the buy price (cost basis) of your mutual funds. When you sell them years later, your taxable gain will be calculated from this higher cost basis, saving you thousands in taxes.
The Large Portfolio Bottleneck
While tax harvesting mutual funds is highly effective for smaller asset bases, it becomes less impactful on its own as your portfolio grows into ₹20 lakhs, ₹30 lakhs, or ₹40 lakhs.
When your portfolio generates several lakhs in capital gains annually, the ₹1.25 lakhs exemption limit becomes a drop in the ocean. Relying solely on a single account's tax exemption will still leave you with massive LTCG tax liabilities on the rest of your growing investments. To combat this, larger investors need to think structurally about portfolio distribution.
The Family Account Strategy: Multiplying Exemption Limits
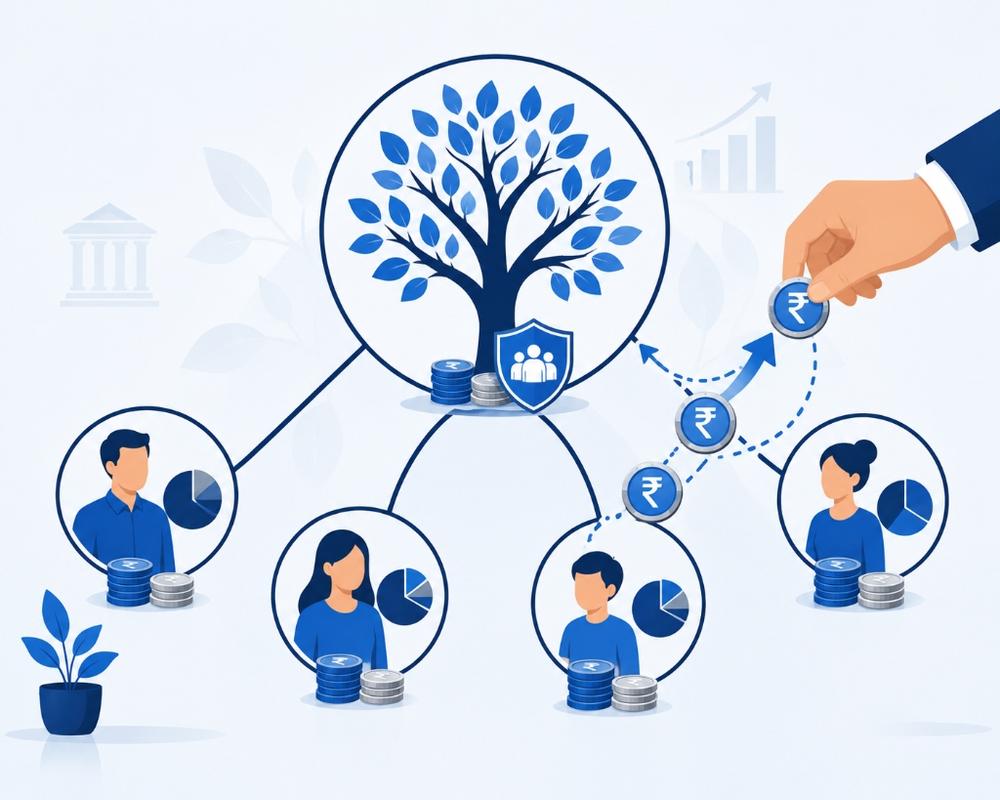
To scale your tax savings as a high-net-worth investor, you should divide your portfolio among family members rather than pooling all your capital into a single account.
By distributing your investments across portfolios belonging to family members—such as your spouse, parents, or adult children—you multiply your tax-saving power:
- Multiple Exemptions: Each family member gets their own independent ₹1.25 lakhs annual LTCG tax exemption.
- Lower Tax Brackets: If certain family members (like retired parents) are in lower overall income tax brackets, you can also optimize short-term gains or dividend distributions through their accounts.
- Resetting the Family Cost Basis: You can execute tax harvesting in each individual family account every year, increasing your family's collective tax-free harvesting threshold to ₹5 lakhs or more.
This method works well in tandem with regular portfolio rebalancing to ensure that your family's overall asset allocation remains aligned with your long-term financial goals.
Final Thoughts
Tax harvesting mutual funds is a simple, legal, and highly effective way to optimize your portfolio's growth. If you have a small portfolio, redeem units annually to lock in tax-free gains up to ₹1.25 lakhs. If your portfolio is large, distribute the capital across family members' accounts to multiply your exemptions and scale your tax savings. By managing your tax liabilities proactively, you keep more of your hard-earned money working for you.