In B2B commerce, profitable businesses go bankrupt every day—not from a lack of sales, but from a lack of cash. In Indian supply chains and commercial contracting, corporate buyers routinely demand 60, 90, or even 120-day payment terms.
If your cash is tied up in raw materials, manufacturing labor, and accounts receivable, you cannot pay your own vendors, taxes, or payroll. Mastering working capital management small business frameworks is the ultimate operational skill that separates fragile operators from enduring market leaders.
1. Motivating Early Inflows with Cash Discounts
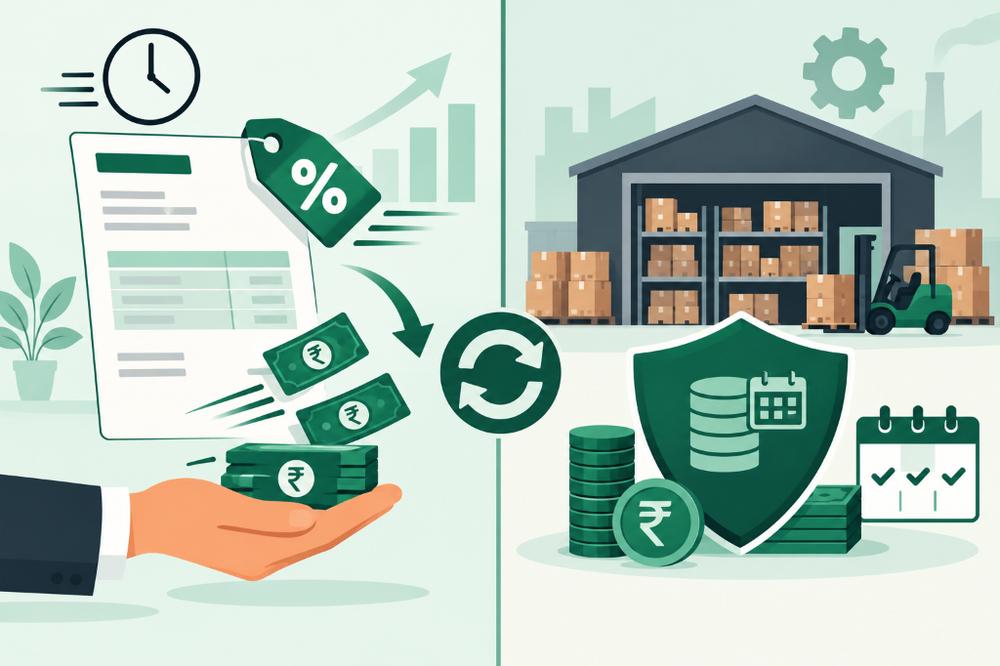
Waiting passively for 90 days to collect on an invoice exposes your balance sheet to severe liquidity risk. The most effective way to protect working capital is to incentivize corporate buyers to settle their balances early.
Implementing a structured early payment cash discount program (such as 1.5% or 2% for payment cleared within 10 to 15 days) is far cheaper than servicing expensive short-term bank credit lines:
- The Buyer’s Incentive: Corporate finance heads are measured on annualized return on cash; a 2% discount on a 90-day invoice translates to a compelling ~8% annualized savings.
- Predictable Cash Velocity: Even if only 30% of your client base adopts early settlement, the accelerated cash inflows fund your daily operations without taking on high-interest debt financing.
2. Managing Delays with Strategic Inventory Leverage
When a large client delays payment past agreed terms, traditional collection tactics—like aggressive emails or legal notices—often destroy the business relationship without producing cash.
To collect overdue receivables without alienating buyers, experienced founders deploy structural operational leverage:
- Sole Vendor Dominance: Strive to become the primary or exclusive supplier for critical components. When a client purchases 100% of a specific SKU from you, they cannot easily bypass you.
- Front-Carrying Buffer Inventory: Hold finished inventory on your shop floor ready for immediate dispatch against just-in-time production schedules.
If an account slips past their payment threshold, holding inventory gives you tactical justification to pause shipments: "Our automated system restricts loading subsequent consignments until previous invoice clearances update." While high-stakes and delicate, this structural control puts legitimate pressure on the client's finance department without personal conflict.
3. The 3-Month Cash Flow Buffer Rule
In commercial contracting, credit cycles rarely run on schedule. An agreed 60-day credit term routinely drifts into 75 or 90 days due to bureaucratic approval bottlenecks, invoice disputes, or seasonal treasury holds.
Because payment drift is inevitable, your working capital policy must mandate an untouchable 3-month cash flow reserve:
- Calculate total non-negotiable monthly outflows: employee payroll, facility rent, utilities, interest obligations, and basic vendor commitments.
- Maintain three times this amount in liquid business bank accounts or overnight funds.
Following a disciplined business emergency fund policy ensures your enterprise operates with confidence, allowing you to reject disadvantageous credit demands and survive sudden market contractions.
Final Thoughts
Working capital management for small businesses is not an accounting chore; it is an active risk management discipline. By incentivizing early payment with cash discounts, maintaining sole-supplier leverage through inventory positioning, and safeguarding three months of liquid operational runway, you insulate your company from predatory credit terms and build an enduring, profitable enterprise.